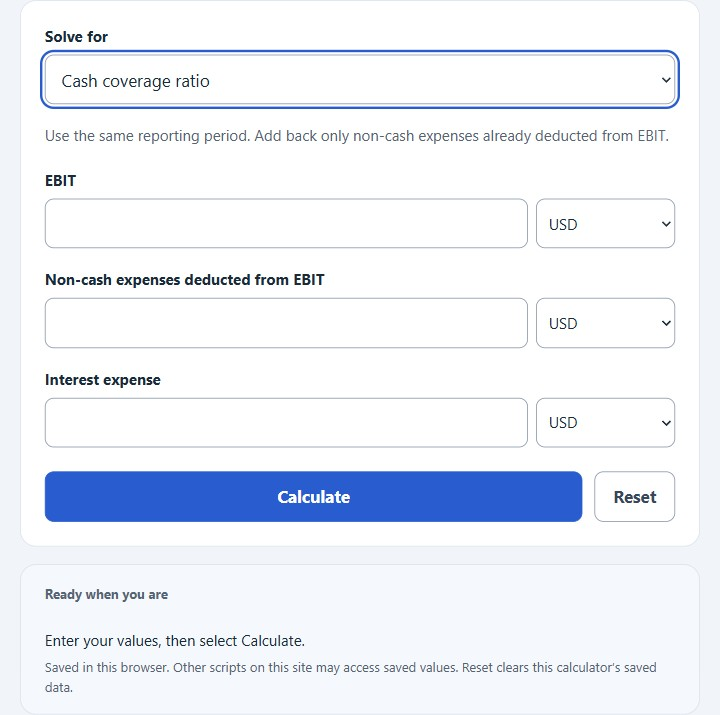
Calculate cash coverage ratio or interest coverage ratio from EBIT, non-cash expenses, and interest expense in units, thousands, or millions.
Cash Coverage Ratio Formula
This calculator uses the earnings add-back cash coverage formula below. Its interest coverage mode uses ICR = EBIT / IE. Amounts may be entered in USD, thousands or millions; the calculator converts each amount to USD.
- Where CCR is the cash coverage ratio
- EBIT is earnings before interest and taxes
- NCE is the non-cash expenses
- IE is the interest expense
Interest expense refers to the cost incurred by a company or individual for borrowing funds or using credit, which is paid as interest to the lender.
Non-cash expenses refer to costs incurred by a business that do not involve an actual cash outflow, such as depreciation or amortization.
Earnings before interest and taxes (EBIT) measures earnings before deducting interest expense and income tax expense.
Cash Coverage Ratio Definition
This calculator uses an earnings add-back version of cash coverage: (EBIT + non-cash expenses already deducted from EBIT) divided by interest expense. When the add-backs are depreciation and amortization, the numerator is EBITDA. This is an earnings proxy, not reported operating cash flow or cash on hand; cash coverage has other definitions, so compare ratios using the same formula.
Use amounts for the same entity and reporting period. Do not add back a non-cash charge that was not deducted from EBIT. The interest coverage mode uses EBIT divided by interest expense, without these add-backs.
A ratio above 1 means the selected numerator exceeds interest expense; 1 means it equals interest expense, and 0.5 means it is half as large. Negative EBIT and coverage are possible. Positive interest expense is required to form either ratio; a zero denominator is undefined.
Higher coverage can indicate more earnings relative to interest, but does not establish cash availability or guarantee payment. Neither mode includes debt principal, working-capital requirements or capital expenditures. Compare consistent definitions across periods and industry peers rather than treating a universal threshold as proof of financial health.
Cash Flow and Cash Debt Coverage
Select Cash flow / cash debt coverage to compare net cash provided by operating activities with a debt or liabilities balance. This uses reported operating cash flow, rather than the EBIT add-back earnings proxy in the default cash coverage mode. Choose the definition required for your analysis:
- Cash flow coverage ratio = operating cash flow / total debt balance. Enter the total debt balance specified by your accounting or lending definition.
- Cash debt coverage ratio = operating cash flow / average total liabilities.
- Current cash debt coverage ratio = operating cash flow / average current liabilities.
For either average, enter the beginning and ending liabilities balances for the cash flow reporting period; the calculator uses (beginning + ending) / 2. Use one entity and consistent definitions. All monetary inputs can use USD, thousands or millions independently. Operating cash flow may be negative; the debt balance or average liabilities denominator must be positive.
For example, operating cash flow of $120,000 and total debt of $400,000 give 120,000 / 400,000 = 0.3 times, or 30%. To use average total liabilities instead, beginning liabilities of $360,000 and ending liabilities of $440,000 also average $400,000. The matching cash debt coverage result is 0.3 times. Select the denominator definition before entering its balances.
These ratios compare cash generated during a period with a balance of obligations. They differ from debt-service coverage, whose denominator is principal and interest payments due for a period. They do not deduct capital expenditures or guarantee repayment capacity. Compare like definitions and reporting periods; no single cutoff establishes financial health.
Cash Coverage Ratio Example
How to calculate the cash coverage ratio?
- First, determine the EBIT.
Calculate the earnings before interest and tax.
- Next, determine the non-cash expenses.
Measure the total non-cash expenses.
- Next, determine the interest expense.
Calculate the total interest expense.
- Finally, calculate the cash coverage ratio.
Calculate the cash coverage ratio using the equation above.
FAQ