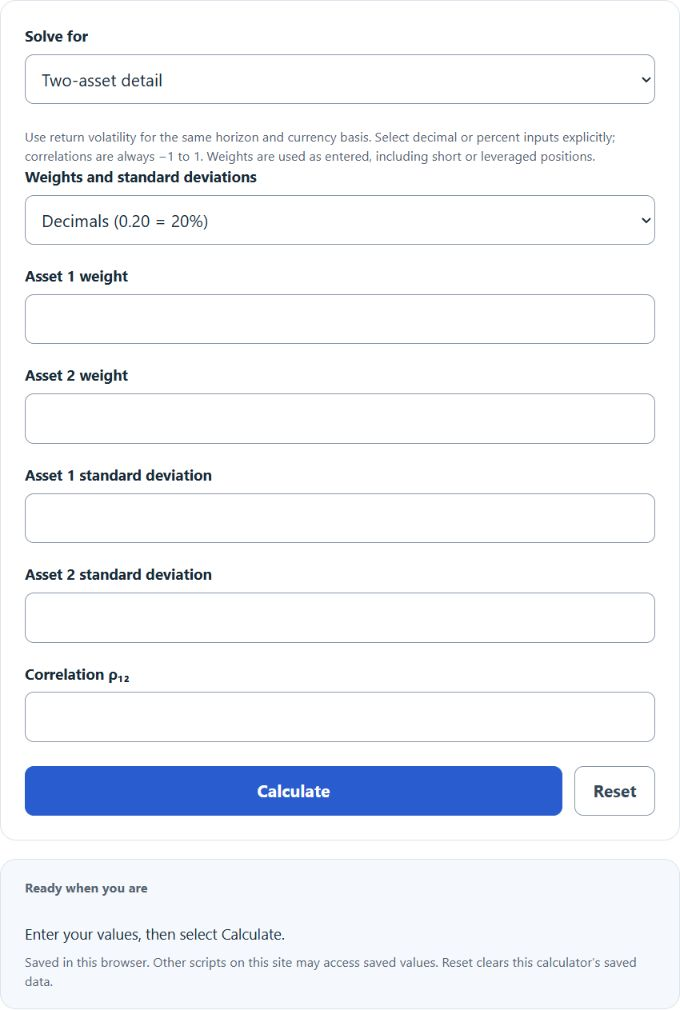
Calculate portfolio variance and standard deviation from asset weights, standard deviations, and correlations for two or more assets.
Portfolio Variance Formula
The following formula is used to calculate the portfolio variance:
PV = w1^2 * σ1^2 + w2^2 * σ2^2 + ... + wn^2 * σn^2 + 2 * w1 * w2 * ρ12 * σ1 * σ2 + ... + 2 * w1 * wn * ρ1n * σ1 * σn + ... + 2 * wn-1 * wn * ρn-1n * σn-1 * σn
Variables:
- PV is the portfolio variance
- w1, w2, ..., wn are the weights of the individual assets in the portfolio
- σ1, σ2, ..., σn are the standard deviations of the individual assets
- ρ12, ρ1n, ..., ρn-1n are the correlation coefficients between the individual assets
To calculate the portfolio variance, square the weight of each asset and multiply it by the square of its standard deviation. Then, for each distinct pair of assets (i, j), compute 2 × wi × wj × ρij × σi × σj. Finally, sum the single-asset terms and all pairwise terms to obtain the portfolio variance.
What is a Portfolio Variance?
Portfolio variance is a statistical measure of the dispersion of a portfolio’s returns (the expected squared deviation of returns from their mean). It is a key concept in modern portfolio theory, which commonly measures risk using the variance (or, more commonly in practice, the standard deviation) of returns. Portfolio variance can be computed from asset weights and the assets’ variances and covariances (or standard deviations and correlation coefficients). The portfolio standard deviation (the square root of the variance) is often called the portfolio’s volatility; higher variance implies higher volatility and risk.
How to Calculate Portfolio Variance?
The following steps outline how to calculate the Portfolio Variance.
- First, determine the weights of each asset in the portfolio.
- Next, determine the variances of each asset in the portfolio.
- Next, determine the covariance between each pair of assets in the portfolio.
- Calculate the squared weights of each asset.
- Multiply the squared weights by the variances of each asset.
- For each distinct pair of assets, calculate 2 × (weighti × weightj × covariance(i,j)).
- Sum up the results from steps 5 and 6.
- The final result is the portfolio variance.
Example Problem:
Use the following variables as an example problem to test your knowledge.
Weights: Asset A = 0.4, Asset B = 0.6
Variances: Asset A = 0.09, Asset B = 0.16
Covariance: Cov(A,B) = 0.04. For this calculator enter standard deviations 0.3 and 0.4 and correlation 0.04/(0.3 × 0.4) = 1/3. The variance is 0.0912 and standard deviation is about 30.20%. Select decimal inputs; all return statistics must use the same period.