Calculate capitalized loan interest by balance timing and exact days, model a later disbursement, reverse-solve inputs, and compare repayment impact.
- All Business Calculators
- WACC Calculator (Weighted Average Cost of Capital)
- Cost of Capital Calculator
- Daily Interest Calculator
Capitalized Interest Formula
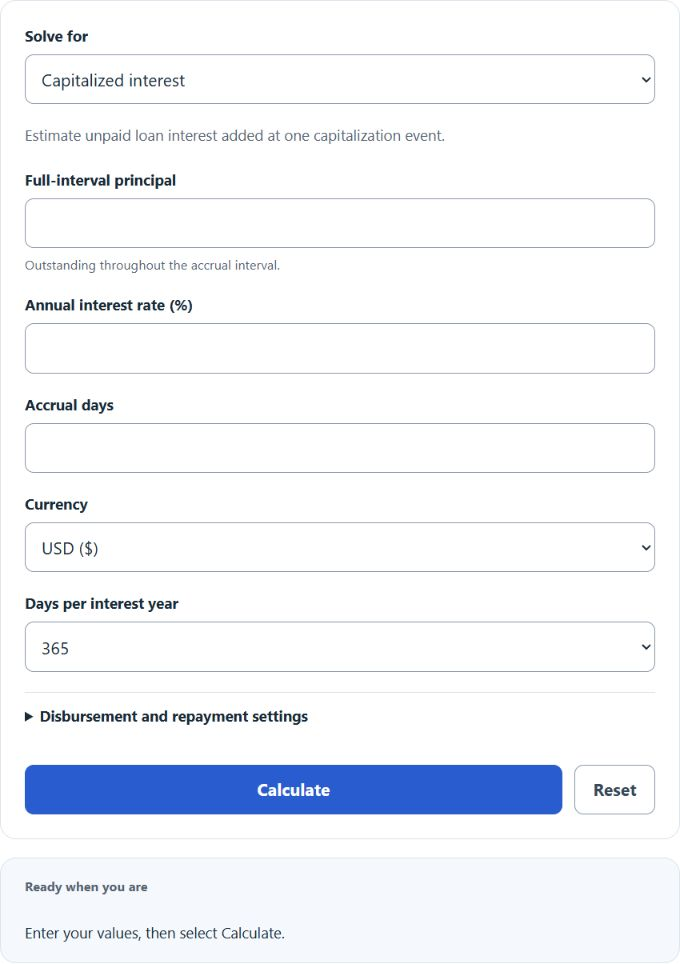
This calculator models unpaid loan interest added to principal at one capitalization event. It offers capitalized interest, starting principal, annual rate, and accrual time. For a full-interval balance P and later disbursement L, accrued interest is P × (r/100) × days/B + L × (r/100) × later days/B. Subtract interest already paid to find the amount added to principal. B is the selected 360, 365, or 365.25-day basis.
For example, $20,000 at 6% for 365 days on a 365-day basis accrues $1,200. If $300 has been paid, $900 capitalizes and the balance becomes $20,900. Repayment estimates assume equal monthly payments at the same fixed rate, excluding fees. Reverse modes use one balance before paid interest. Currency selection changes the symbol only.
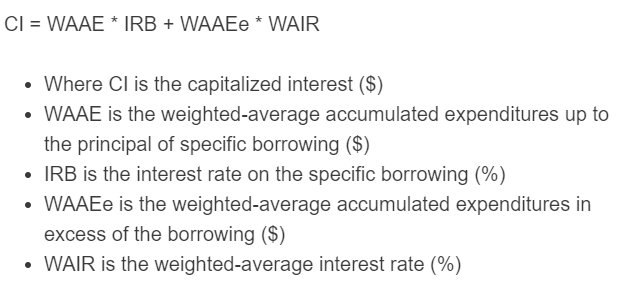
Capitalized interest is the borrowing cost added to the cost of a qualifying asset, such as a building or construction project, instead of being expensed immediately. The asset-accounting formulas below describe a separate use of the term; the loan calculator above does not compute weighted-average construction expenditures or determine qualifying capitalization costs.
Quick estimate formula for asset accounting
- CI = capitalized interest
- WAAE = weighted-average accumulated expenditures, or average accumulated expenditures
- r = capitalization interest rate as a percentage
- m = construction period in months
Specific borrowing plus excess borrowing formula for one year
- CI = capitalized interest
- SB = expenditures covered by specific borrowing
- r1 = rate on the specific borrowing as a percentage
- EB = expenditures above the specific borrowing amount
- r2 = weighted-average rate on other debt as a percentage
The accounting quick estimate applies an average expenditure amount over a construction period. The specific-plus-excess expression shown assumes one full year; a shorter qualifying period needs the corresponding time factor. These are accounting illustrations, not selectable modes in this loan calculator. Accounting eligibility and limits require the applicable standards.
Capitalization Rate and Input Reference
| Input | What it represents | Common notes |
|---|---|---|
| Average accumulated expenditures | The weighted average amount spent on the asset during the capitalization period. | Often lower than total project cost if spending occurs gradually. |
| Capitalization interest rate | The interest rate applied to qualifying expenditures. | Use the specific borrowing rate first, then the weighted-average rate on other debt if needed. |
| Construction period | The portion of the year during which interest is capitalized. | A 6-month period is entered as 6, which applies 6/12 of annual interest. |
| Excess borrowing | Qualifying expenditures not covered by specific project debt. | Apply the weighted-average rate from other outstanding borrowings. |
Illustrative Interest Rate Scenarios
These rates are arithmetic illustrations, not current market ranges or recommendations. Use the rate specified by the actual loan.
| Rate range | Typical use | Effect on capitalized interest |
|---|---|---|
| 4% to 5% | Illustrative lower-rate scenario | Lower capitalized interest |
| 6% to 7% | Illustrative middle-rate scenario | Moderate capitalized interest |
| 8% to 10%+ | Illustrative higher-rate scenario | Higher capitalized interest |
Examples
Example 1: Quick estimate
You have average accumulated expenditures of $500,000, a capitalization rate of 6%, and a 12-month construction period.
The capitalized interest is $30,000.
Example 2: Specific borrowing plus excess borrowing
You have $300,000 covered by specific borrowing at 5% and $200,000 of excess expenditures financed at a weighted-average rate of 7%.
The specific borrowing portion is $15,000, and the excess borrowing portion is $14,000. The total capitalized interest is $29,000.
FAQ
What is capitalized interest?
For this loan calculator, it means unpaid accrued interest added to the loan principal. Actual capitalization events depend on the loan terms and applicable rules. See MOHELA’s daily interest and capitalization explanation. In asset accounting, the term has the distinct meaning described below.
Capitalized interest is interest cost that is added to the cost basis of a qualifying asset instead of being recorded as an immediate interest expense. It is commonly used for assets that take time to get ready for use, such as buildings, major equipment, and construction projects.
When should interest capitalization start and stop?
Interest capitalization generally starts when expenditures for the asset have been made, activities needed to prepare the asset are in progress, and interest cost is being incurred. It generally stops when the asset is substantially complete and ready for its intended use.
Why use weighted-average accumulated expenditures?
Weighted-average accumulated expenditures reflect the timing of spending during the construction period. If you spend money gradually, you did not borrow or use funds for the full project cost for the entire period. Using a weighted average gives a more accurate interest capitalization amount than applying the rate to total project cost.