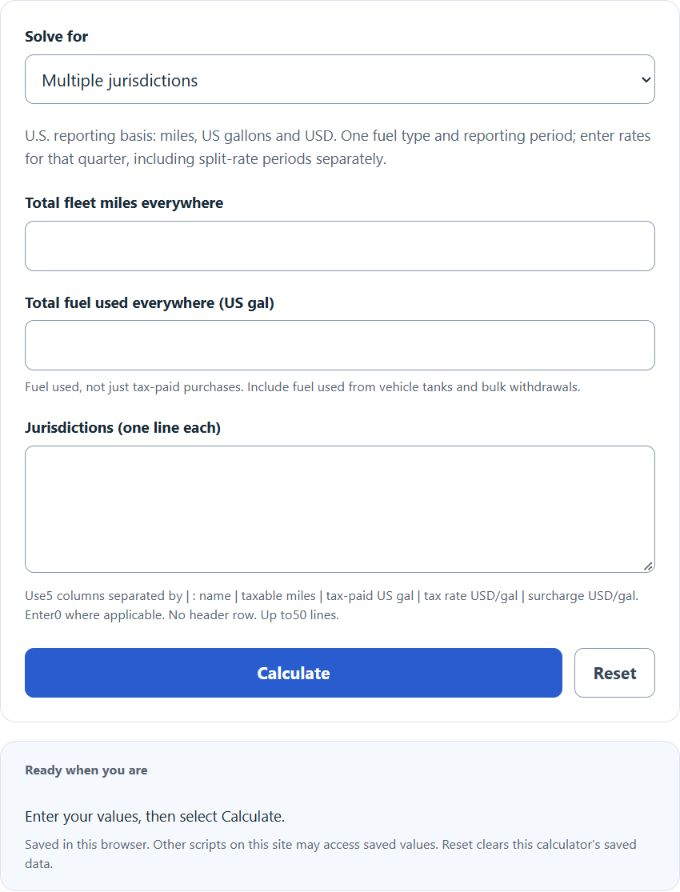
Estimate IFTA tax or credit from taxable miles, eligible tax-paid gallons and fleet fuel economy. Uses user-entered quarter-specific rates on a U.S. reporting basis: miles, US gallons and USD.
IFTA Fuel Tax Formula
IFTA fuel tax is worked out in four steps, repeated for every jurisdiction you traveled in during the quarter.
Fleet MPG = Total Miles / Total Fuel Used
Taxable Gallons = Jurisdiction Taxable Miles / Fleet MPG
Net Taxable Gallons = Taxable Gallons - Tax-Paid Gallons
Tax Due = Net Taxable Gallons * Tax Rate
Where a surcharge applies for the fuel and quarter, it is calculated separately:
Surcharge = Taxable Gallons * Surcharge Rate
The variables are:
- Total Miles: every fleet mile, including IFTA and non-IFTA operations, for the same fuel and reporting period.
- Total Fuel Used: all fuel used by the qualified fleet, including fuel from vehicle tanks and bulk withdrawals; this is independent of documented tax-paid purchase credits.
- Fleet MPG: your average miles per gallon for the quarter, applied to every jurisdiction.
- Jurisdiction Miles: taxable miles in a jurisdiction, excluding eligible exempt and trip-permit miles; those miles still belong in total fleet miles.
- Taxable Gallons: the fuel IFTA treats as burned in that jurisdiction, based on miles and MPG.
- Tax-Paid Gallons: fuel you bought, and paid tax on at the pump, inside that jurisdiction.
- Net Taxable Gallons: taxable gallons minus tax-paid gallons; a negative value is a credit.
- Tax Rate: that jurisdiction’s fuel tax per gallon for the quarter.
- Surcharge Rate: the separate per-gallon surcharge applicable to that fuel, jurisdiction and quarter.
The calculator retains three tasks. Multiple jurisdictions uses separate fleet totals plus one input line per jurisdiction or split-rate period: name | taxable miles | tax-paid US gallons | regular USD/US-gallon rate | surcharge USD/US-gallon rate. Single jurisdiction uses a supplied fleet MPG. Fleet MPG only divides total fleet miles by total fuel used. All rows use one fuel and reporting period. Totals retain full precision internally; follow base-jurisdiction rounding when filing.
Quarter-Specific Rates and Surcharges
Use the official IFTA quarterly rate matrix for your fuel and reporting period. Rates must already be normalized to USD per US gallon, including Canadian jurisdiction rates. Do not convert an already normalized rate a second time. The calculator does not retrieve rates.
| Rate input | Required basis |
|---|---|
| Regular rate | Applicable fuel and quarter, USD/US gal |
| Canadian jurisdiction rate | Already normalized to USD/US gal |
| Split-rate period | Separate miles and credits under each rate |
A surcharge is billed on taxable gallons without an offset for tax-paid purchases and is reported separately from regular tax. Verify applicability for your fuel and quarter instead of assuming a fixed list of jurisdictions.
| Charge | Gallons used in calculation |
|---|---|
| Regular tax | Taxable gallons minus eligible tax-paid gallons |
| Surcharge | All taxable gallons; no purchase offset |
Enter a surcharge rate of0 where none applies. See New York IFTA-101 instructions for the separate regular-tax and surcharge formulas and Illinois fleet fuel-use instructions. This estimate excludes filing, interest, penalties and special distance taxes.
Example IFTA Fuel Tax Calculations
Example 1: One state, tax owed
Illustrative example, not a current rate quote:10,000 taxable miles, fleet MPG6.0,1,200 eligible tax-paid US gallons, and regular rate0.20USD/US gal.
- Taxable gallons: 10,000 / 6.0 = 1,666.67
- Net taxable gallons: 1,666.67 – 1,200 = 466.67
- Tax due: 466.67 x $0.20 = $93.33
The unrounded arithmetic gives an estimated$93.33 owed; apply the base jurisdiction’s required rounding for a return.
Example 2: A surcharge state
Illustrative surcharge example, not a current rate quote:5,000 taxable miles at6.0MPG, no tax-paid fuel credit, regular rate0.22USD/US gal and surcharge0.105USD/US gal.
- Taxable gallons: 5,000 / 6.0 = 833.33
- Base tax: 833.33 x $0.22 = $183.33
- Surcharge: 833.33 x $0.105 = $87.50
- Total owed: $183.33 + $87.50 = $270.83
The surcharge is figured on all 833.33 taxable gallons, not on net gallons, and buying fuel in Kentucky would not reduce it.
Frequently Asked Questions
How do I calculate IFTA fuel tax?
Divide total fleet miles everywhere by total fuel used everywhere for that fuel and reporting period to get fleet MPG. For each jurisdiction, divide the miles you drove there by that MPG to get taxable gallons, subtract the tax-paid gallons you bought in that jurisdiction, and multiply the result by the jurisdiction rate. A positive number is tax owed and a negative number is a credit. Add every jurisdiction together for your net tax due or refund for the quarter.
How are the Kentucky and Virginia surcharges calculated?
The surcharge rate is multiplied by your taxable gallons, which is the fuel you burned based on miles and MPG, not by your net gallons. Because the surcharge is not collected at the pump, you cannot claim a credit for fuel you bought in those states against it, so the surcharge is always an amount owed. It is reported on a separate line from the base tax.
Do I owe IFTA tax in a state where I bought no fuel?
Yes. IFTA tax follows the miles you drive, not where you fuel up. If you drove miles in a jurisdiction but bought no fuel there, all of your taxable gallons in that jurisdiction are owed, offset only by credits from fuel you paid tax on elsewhere.