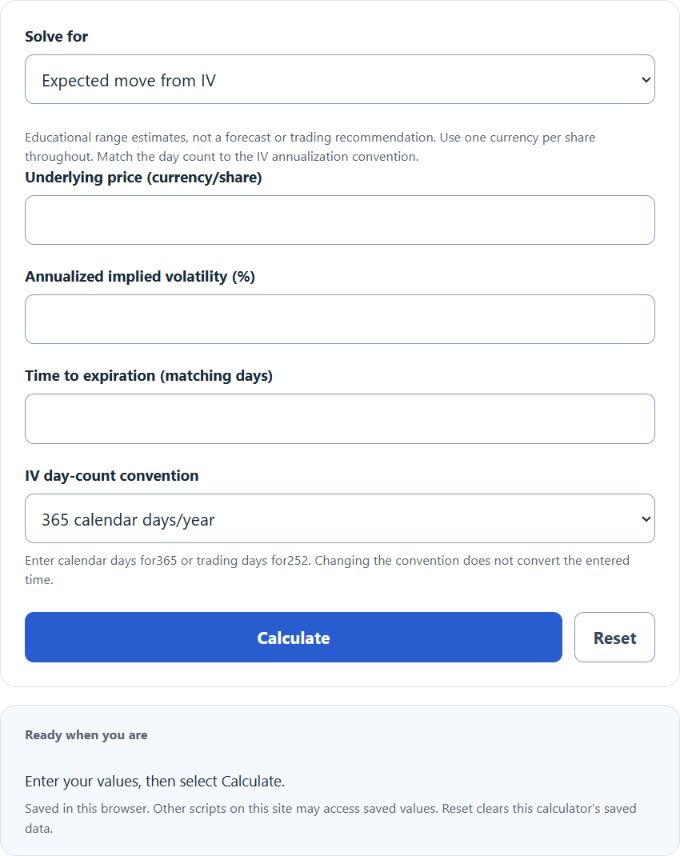
Estimate an underlying-price move from annualized IV, use an ATM-straddle pricing heuristic, or reverse-solve IV. Day-count conventions and the meaning of each range are shown explicitly.
Options Expected Move Formula
This approximation estimates a move in the underlying price from annualized implied volatility. It does not calculate an option premium or predict direction.
EM = S × IV × √(T / B)
Variables:
- EM is the approximate absolute underlying-price move in currency per share
- S is the current price of the underlying asset
- IV is annualized implied volatility as a decimal (20% = 0.20)
- T is time until expiration; B is the matching annualization basis:365 calendar days or252 trading days
Multiply spot by decimal IV and by the square root of the matching year fraction. The reverse calculation is IV = EM ÷ S ÷ √(T/B). A straddle-based move instead uses the ATM call-plus-put premium times the selected multiplier. The100% and85% choices are heuristics; neither makes the straddle range a sigma confidence interval.
What is an Options Expected Move?
An IV-based expected move is a simplified, symmetric measure of price variation. The one- and two-sigma labels assume a suitable constant-volatility model, not guaranteed real-world coverage. Jumps, skew and changing volatility can make actual outcomes differ. This is educational information, not a trading recommendation.
How to Calculate Options Expected Move?
The following steps outline how to calculate the Options Expected Move using the given formula:
- First, determine the current price of the underlying asset (S).
- Next, determine the implied volatility of the option (IV).
- Next, determine the time until expiration in days (T).
- Use EM = S × IV × √(T/B), matching days to the selected calendar or trading-day convention.
- Finally, calculate the Options Expected Move (EM).
- After inserting the variables and calculating the result, check your answer with the calculator above.
Example Problem:
Use the following variables as an example problem to test your knowledge:
Current price of the underlying asset (S) = $50
Implied volatility of the option (IV) = 0.2
Time until expiration (T) =90 calendar days, B =365. With S =$50 and IV =0.20 (enter20%), EM ≈$4.9656, or9.9313%. The simple1× band is approximately$45.0344 to$54.9656.