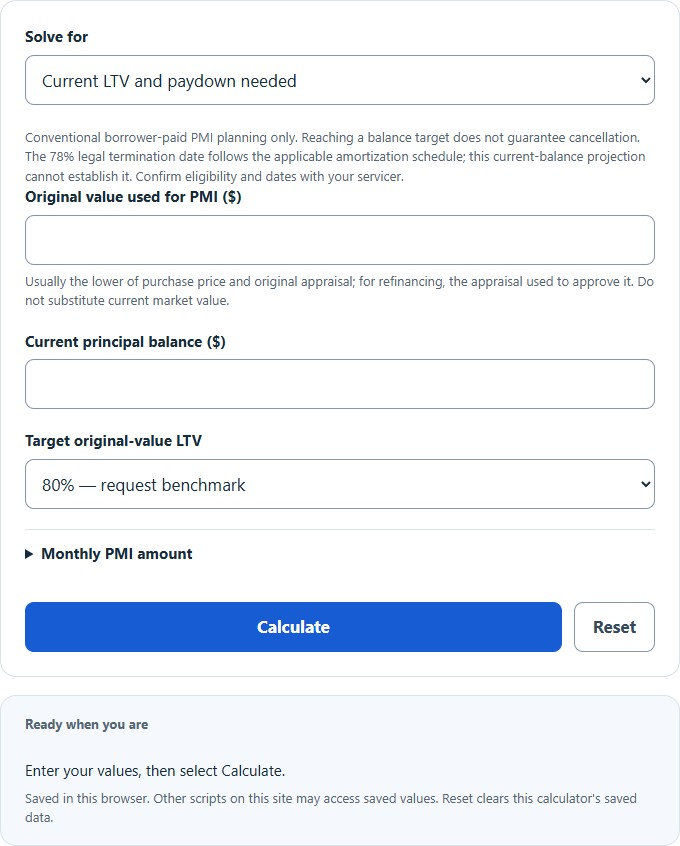
Estimate your original-value loan-to-value ratio, the principal paydown needed to reach 80% or 78%, and when your balance may reach that target.
Remove PMI Formula
PMI removal is usually driven by loan-to-value (LTV), not by time alone. In simple terms, the more equity you have in the home, the closer you are to removing private mortgage insurance. This calculator estimates balance targets for conventional borrower-paid PMI planning. The 80% request benchmark and 78% scheduled-termination benchmark are different rules; reaching a modeled target does not guarantee removal.
Use the current unpaid principal and original value used for PMI, not the original loan amount or today’s market estimate. Original value is generally the lower purchase price or original appraisal; a refinance uses the appraisal relied on for approval. LTV in the equations is a ratio; multiply by 100 for a percentage. The original-value difference is not present market equity.
What the Variables Mean
- Original PMI Value – the property value defined for the applicable original-value benchmark.
- Target LTV – 80%, 78%, or a supplied planning percentage of original PMI value.
- Loan Balance – the unpaid principal remaining on the mortgage.
- LTV – current principal as a percentage of original PMI value in this tool.
- Original-value difference – original PMI value minus current principal; current market equity requires a current valuation.
How to Use the Remove PMI Calculator
- Enter the original value used for PMI from your loan documents.
- Enter current unpaid principal from your latest statement.
- Select a balance target. For a time projection, also supply the note rate, monthly principal-and-interest payment and starting date.
- Review paydown needed or modeled payment count; optional extra principal and constant PMI are planning inputs.
- If you appear to be in range, contact your loan servicer and ask what documentation is required for PMI removal.
Why PMI Gets Removed
PMI is generally charged on conventional mortgages when the borrower starts with less than 20% equity. Principal paydown reduces original-value LTV. For covered loans, an 80% cancellation request has conditions; automatic termination normally follows the applicable schedule’s 78% date when current. Extra payments can advance request eligibility but do not advance that statutory termination date. Ask the servicer for the applicable schedule and midpoint backstop.
| Factor | Why It Matters |
|---|---|
| Current loan balance | This is the number most directly used to measure your actual LTV. |
| Home appreciation | Appreciation can support separate investor or servicer policies; it does not change the original value used by this model. |
| Extra principal payments | Paying down principal faster lowers LTV sooner. |
| Payment history | A request requires current payments and good payment history; scheduled automatic termination requires being current. |
| Valuation method | The lender may rely on an automated estimate, broker opinion, or formal appraisal. |
Example
Assume the original PMI value is $320,000 and current unpaid principal is $250,000. First, calculate the LTV:
Next, calculate the 80% original-value balance benchmark:
Because the remaining balance of $250,000 is below $256,000, the loan is under 80% LTV. This meets the modeled balance benchmark for a request; cancellation still depends on applicable conditions and servicer confirmation.
Important Interpretation Notes
- Request and termination dates differ. A current-balance projection cannot reconstruct the statutory amortization schedule after earlier prepayments or schedule changes.
- Original loan amount is not the same as current balance. If you have made payments for years, your balance may be much lower than the original amount.
- Current value is a separate question. Appreciation-based investor policies are not modeled here.
- Removing PMI lowers the monthly payment. It usually removes the insurance portion, not the principal-and-interest portion of the mortgage.
- This is a planning tool. Request conditions include a written request, current payments and good history, plus applicable evidence concerning value decline and junior liens. These ordinary rules do not cover every loan: high-risk, FHA/VA/USDA and lender-paid insurance need separate rules.
Common Questions
Does a rising home value help remove PMI faster?
Yes, if your loan investor allows you to request PMI removal based on current value. Divide your current principal balance by the property value accepted by your servicer and multiply by 100 to get current-value LTV.
For a Fannie Mae loan on a one-unit primary residence or second home, the current-value LTV limit is 75% for loans two through five years old and 80% for loans older than five years. Qualifying improvements can allow an earlier request at 80% LTV or less. Your servicer checks the applicable investor rules, valuation and payment history. The calculator above uses the original value benchmarks.
Is 20% equity the same as 80% LTV?
Yes. They describe the same position from opposite angles: owning 20% of the home means the loan represents 80% of the value.
Will removing PMI change my interest rate?
Usually no. PMI removal generally reduces the payment by eliminating the mortgage insurance charge, while the loan’s interest rate and repayment schedule stay the same unless you refinance or modify the mortgage.
What should I check before asking for PMI removal?
Review the PMI disclosure, original PMI value, current principal, payment history and applicable cancellation or termination schedule. Ask the servicer which conditions and documents apply. A time projection assumes a constant note rate and monthly payments beginning one month after the supplied date; it excludes daily accrual, fees and servicer rounding.
Common Mistakes to Avoid
- Substituting current market value for original PMI value.
- Assuming the original loan amount equals the current balance.
- Ignoring the effect of extra principal payments already made.
- Focusing only on monthly payment instead of total equity position.
- Confusing a modeled 78% balance crossing with the legal scheduled-termination date.
Use the balance estimate as a checkpoint, then verify eligibility and dates with your servicer. See the CFPB’s PMI cancellation guidance and its cancellation and termination bulletin.