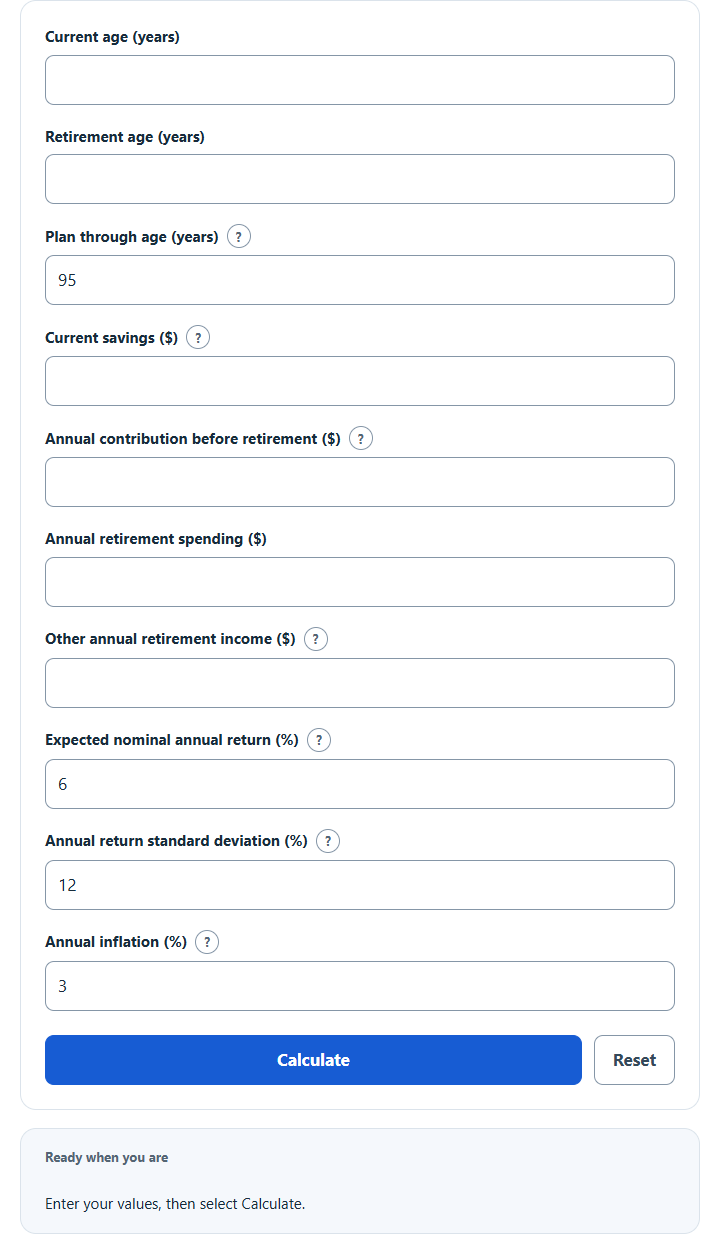
Estimate the probability your retirement savings will last, and to what age, with a Monte Carlo simulation of your savings, contributions and spending.
Retirement Success Probability Formula
The model simulates many possible market futures and counts how often your money lasts. Each simulated path updates your balance one year at a time:
B(t+1) = B(t) x (1 + r(t)) + C(t) - W(t)
Where:
Nsuccess is the number of simulated paths in which the balance never drops below zero through your planning age.
Ntotal is the total number of simulated paths (this calculator uses 2,000).
B(t) is the portfolio balance at the start of year t, in today’s dollars.
The nominal annual return is drawn independently from the entered normal distribution, with losses capped at 100%. Real growth is max(0,1+nominal return)/(1+inflation). Contributions and withdrawals occur at year-end. A fixed seed makes identical inputs reproducible. Taxes, fees, mortality and changing cash flows are excluded.
C(t) is your contribution during year t, applied only in the years before retirement.
W(t) is your net withdrawal during year t in retirement, equal to annual spending minus any other retirement income.
A path counts as a success when no retirement-year withdrawal produces a negative balance; exactly zero after the final withdrawal is sufficient. The probability of success is simply the share of all paths that succeed.
Interpreting Your Result
A higher simulated survival percentage means more paths met the withdrawals under the entered assumptions. The ranges below describe this model’s sampled outcomes, not real-world confidence or a recommended planning target.
| Probability of success | Reading |
|---|---|
| 90% to 100% | At least 90% of the sampled paths met all withdrawals. |
| 75% to 89% | 75% to 89% of the sampled paths met all withdrawals. |
| 50% to 74% | 50% to 74% of the sampled paths met all withdrawals. |
| Below 50% | Fewer than 50% of the sampled paths met all withdrawals. |
Common Planning Assumptions
The return, volatility and inflation defaults are illustrative assumptions, not forecasts or calibrated portfolio estimates. Adjust them for the scenario you intend to test.
| Input | Illustrative range | Default used |
|---|---|---|
| Expected annual return | 4% to 8% | 6% |
| Return volatility (std dev) | 8% to 18% | 12% |
| Inflation | 2% to 4% | 3% |
Example Calculations
Example 1. You are 40, plan to retire at 65, and want the plan to last through age 90. You have $300,000 saved, add $20,000 each year, expect to spend $55,000 per year, and will receive $25,000 from Social Security. Net withdrawal is $30,000 per year. With the default 6% return, 12% volatility, and 3% inflation, this reproducible simulation has 1815 of 2,000 paths meet all withdrawals (90.75%). This is a sampled model result, not a forecast.
Example 2. You are 50, plan to retire at 62, and want coverage through age 92. You have $120,000 saved, add $8,000 a year, plan to spend $60,000, and expect $18,000 of other income. Net withdrawal is $42,000 per year over a 30-year retirement. In this reproducible simulation, 6 of 2,000 paths meet all withdrawals (0.3%). Changing assumptions changes the result; this model does not prescribe a retirement decision.
Frequently Asked Questions
What does probability of success actually mean? It is the percentage of simulated market histories in which your savings last through your chosen planning age. A result of 85% means the plan survived in 85 out of every 100 simulated futures, including many with poor returns.
Why is a probability of 100% not the goal? A 100% result means all 2,000 sampled paths met withdrawals under these assumptions. It does not guarantee future success or establish that you are saving too much. This simplified model does not recommend a target probability.
Why does the result use today’s dollars? Returns are converted to real, inflation-adjusted values, so your spending keeps the same buying power every year. This lets you judge the outcome in money you understand now rather than inflated future figures.