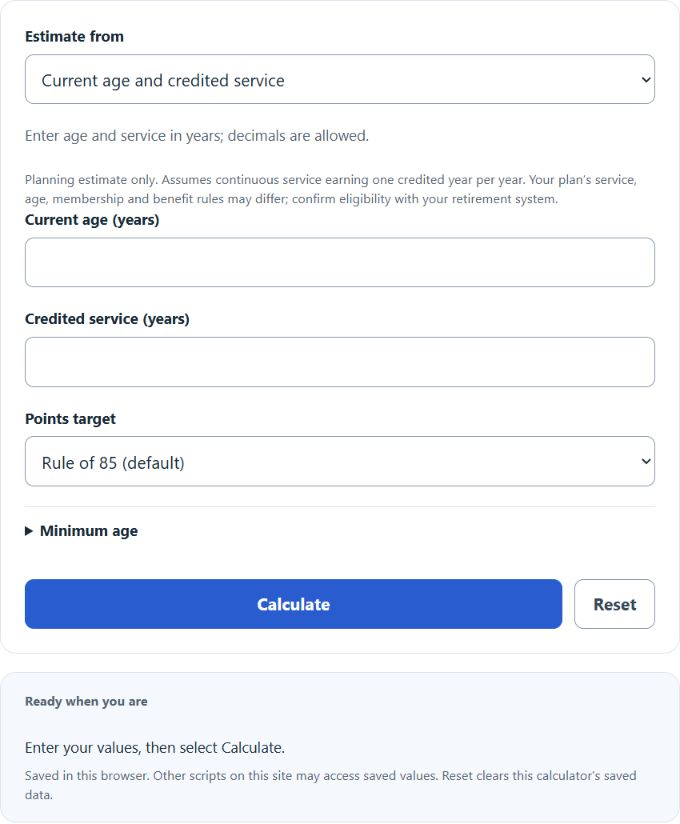
Calculate the Rule of 85 for retirement: enter your age and years of service, or the age you started, to see your points and when you reach 85.
Rule of 85 Formula
The following formula is used to calculate the Rule of 85.
Variables:
- R85 is the Rule of 85 score
- A is the age of the employee (years)
- Y is the number of years of credited service
A score of at least 85 meets the points condition of a Rule of 85 provision. Whether benefits can start without an early-payment reduction also depends on the applicable plan, membership tier, age, credited-service requirements and benefit protections. The calculator tests only the selected points target and entered minimum age.
What Is the Rule of 85?
The Rule of 85 is an age-plus-service provision used by some defined benefit pension plans. Under the applicable plan rules, meeting the threshold may allow payment without an early-retirement reduction. It does not guarantee a maximum pension or override other eligibility conditions, and some protections apply to only part of the benefit.
This provision is not universal. Examples occur in U.S. public pension systems and in protections for some Local Government Pension Scheme members in England and Wales. Always identify the particular plan and membership category before using a threshold.
Where the Rule of 85 Applies
United States
U.S. examples differ by plan and tier. Illinois SERS Tier 1 lists a Rule of 85 route using age and service in years and whole months. Wyoming’s Public Employee Pension Plan also uses 85 points. KPERS 1, generally for employees hired before July 1, 2009, includes an 85-point route. New Mexico PERA Tier 2 applies 85 points with at least five years of service to specified general-member plans, rather than every PERA plan. Texas TRS still uses the Rule of 80; minimum age and service requirements depend on membership history. These examples do not make this generic calculator a plan-specific eligibility tool.
United Kingdom (LGPS)
For the LGPS in England and Wales, membership at any time from April 1, 1998 through September 30, 2006 may carry 85-year-rule protection. Age and membership are measured in full years, not the decimal-year model used here. Protection can cover some or all benefits and depends on individual dates and circumstances. For full retirement before age 60, the rule does not apply automatically; employer discretion may matter. Ask the pension fund for a benefit estimate.
Minimum Age Requirements
Meeting the 85-point threshold alone does not always guarantee eligibility. Many plans layer a minimum age requirement on top of the rule. For example, a plan may require that the member be at least 55 or 60 before the rule can be applied, even if their combined score exceeds 85 at a younger age. Illinois SERS Tier 1 is an exception, allowing retirement at any age once the 85 threshold is met. In the UK LGPS, the rule generally applies only from age 60 onward for protected members, though employers have discretion to allow it earlier.
For example, age 50 plus 35 years of credited service gives 85 points. If the applicable plan also requires age 55, the points condition alone does not establish eligibility. Enter a known minimum age in the optional field, and confirm any other conditions with the plan.
Actuarial Reduction Avoided
An applicable Rule of 85 provision can reduce or remove an early-payment reduction. Reduction formulas vary: they may use a flat percentage, different percentages by age band, or actuarial factors. The Bureau of Labor Statistics glossary uses rates such as 3% and 6% as illustrations of reduction methods, not universal current rates for pension plans. This calculator does not estimate a pension amount or reduction.
For illustration, a plan applying a simple 6% reduction for each of five early years would reduce the applicable benefit by 30%. Actual plan formulas can differ. Meeting an applicable Rule of 85 provision may remove that early-payment reduction from protected benefits; it does not necessarily make the entire pension unreduced.
Rule of 85 vs. Rule of 80 vs. Rule of 90
The points targets 80, 85 and 90 are different arithmetic thresholds. A lower target is reached sooner only when the other modeled conditions are the same. Texas TRS uses the Rule of 80 with membership-dependent age and service requirements. OMERS uses 85/90 factors according to normal retirement age, alongside early-retirement age and service rules; benefit changes can affect eligibility for those factors. Choosing 80, 85, 90 or a custom value here does not load those plans’ complete rules.
As a mathematical illustration with continuous service from age 25 and no additional minimum age, targets of 80, 85 and 90 are reached at ages 52.5, 55 and 57.5 respectively, with 27.5, 30 and 32.5 years of service. These are model outputs, not pension-payment forecasts or plan-specific retirement ages.
Eligibility Scenarios by Starting Age
In this continuous-service model, starting age helps determine when the selected points target is reached. The following Rule of 85 examples assume one service year per elapsed year, no service breaks and no additional minimum age:
Starting at age 20: eligible at age 52.5 (32.5 years of service). Starting at age 25: eligible at age 55 (30 years). Starting at age 30: eligible at age 57.5 (27.5 years). Starting at age 35: eligible at age 60 (25 years). Starting at age 40: eligible at age 62.5 (22.5 years). Starting at age 45: eligible at age 65 (20 years).
These figures represent the mathematical eligibility point. Actual eligibility may be later if the plan imposes a minimum age requirement or if the employee has gaps in service.
Service Credit and What Counts
Not all employment time automatically counts as credited service. Most plans count only periods during which the employee was actively contributing to the pension fund. Leave without pay, unpaid sabbaticals, and periods of reduced hours may not count, or may count at a reduced rate. Some plans allow members to purchase service credit for prior public employment, military service, or periods of leave, but this typically requires an out-of-pocket payment that can be substantial.
In the LGPS in England and Wales, part-time membership counts at its full calendar length for the 85-year rule. For example, ten calendar years of half-time membership count as ten years for that rule. The amount of pension is a separate calculation, and the rule uses full years.
Key Limitations
This age-plus-service provision concerns applicable defined benefit pension plans. It is not an eligibility or withdrawal rule for a 401(k), 403(b), IRA or other defined contribution account. The calculator does not assess benefit amounts, vesting, alternative retirement routes, membership tiers, service-credit rounding, survivor choices or tax consequences. If your pension plan does not use the entered provision, reaching its modeled points target does not create a retirement entitlement.