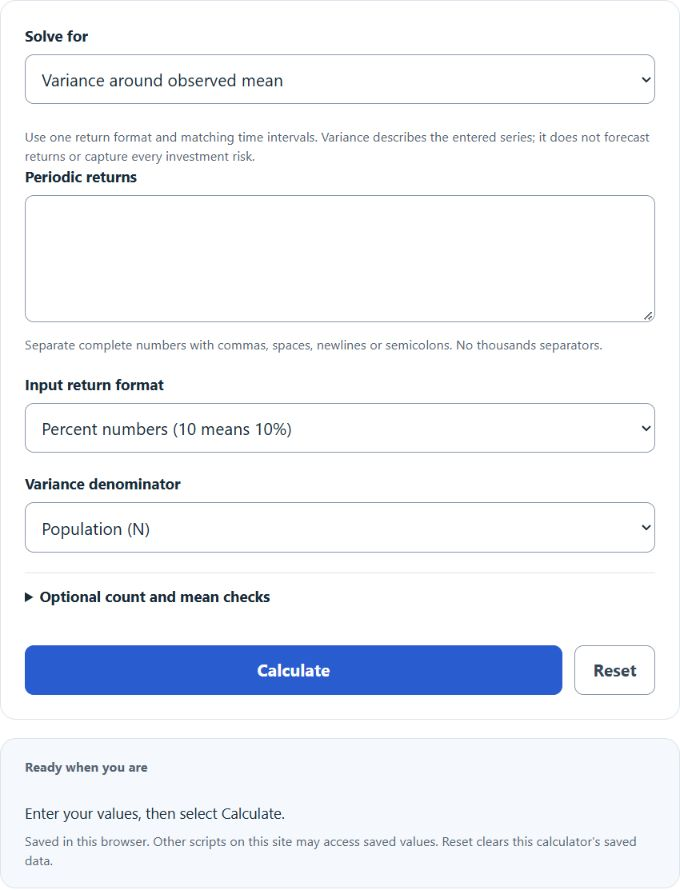
Calculate sample or population variance of periodic returns, verify an optional mean and count, or measure squared deviation from a separate reference return.
Variance Of Returns Formula
Variance of returns measures how widely a series of periodic returns is spread around its average return. In finance, it is a core volatility metric used to compare the consistency of assets, strategies, and portfolios. A larger variance means returns are more dispersed; a smaller variance means returns are clustered more tightly around the mean.
Choose population variance (divide by N) or sample variance (divide by N−1, requiring at least two observations). Variance is centered on the observed arithmetic mean. A different reference belongs in reference mode, which reports mean squared deviation with denominator N rather than calling it variance.
Variable Definitions
| Term | Meaning |
|---|---|
| Variance of returns | The average of the squared deviations from the mean return. |
| Individual return | One observed return from the series being analyzed. |
| Mean return | The arithmetic average of all returns in the set. |
| Total number of returns | The number of observations included in the calculation. |
How to Calculate Variance of Returns
- List all returns for the same asset, portfolio, or strategy over matching time periods.
- Find the mean return.
- Subtract the mean from each return to get each deviation.
- Square each deviation so that positive and negative deviations do not cancel out.
- Add the squared deviations together.
- Divide by N for population variance or N−1 for sample variance.
If you still need the average return, use:
Why Variance Matters
- Risk measurement: Variance is a direct measure of return dispersion and is widely used as a volatility proxy.
- Comparison: Two investments can have the same average return but very different variability.
- Portfolio analysis: Variance is a building block for covariance, correlation, and portfolio risk calculations.
- Strategy evaluation: Lower variance often indicates more stable period-to-period performance.
Interpreting the Result
- A higher variance means returns fluctuate more around the average.
- A lower variance means returns are more consistent.
- A variance of zero means every observed return is identical.
- Variance is expressed in squared return units, so it is often converted into standard deviation for easier interpretation.
Standard deviation is the square root of variance:
Choose the input format explicitly: 10 in percent-number format means 10%, while 0.10 in decimal format means 10%. Percent-number variance uses squared percentage points; divide by 10,000 to convert it to decimal return². Use one format and matching intervals throughout. No automatic annualization is performed.
Example
Suppose five periodic returns are 10%, 15%, 12%, 8%, and 9%.
The population variance is 6.16 squared percentage points (0.000616 in decimal return²), and the standard deviation is about 2.482 percentage points around the 10.8% mean. Sample variance for these same five observations is 7.70 squared percentage points. These statistics do not by themselves establish an investment’s risk level.
Population Variance vs. Sample Variance
The formula above is appropriate when the return set being analyzed is treated as the full population for that period. If the returns are only a sample and you want the sample variance, divide by one less than the number of observations instead.
Common Mistakes to Avoid
- Mixing decimal returns and percentage returns in the same calculation.
- Using returns from different time intervals, such as mixing monthly and annual observations.
- Rounding the mean too early, which can slightly distort the final variance.
- Assuming high variance is always bad; it indicates volatility, not necessarily poor performance.
- Confusing variance with standard deviation; standard deviation is usually easier to interpret because it returns to the original units.
Practical Uses
- Evaluating how stable a stock or fund has been over time.
- Comparing multiple investments with similar average returns.
- Estimating risk before position sizing or allocation decisions.
- Supporting broader portfolio metrics such as diversification and volatility analysis.