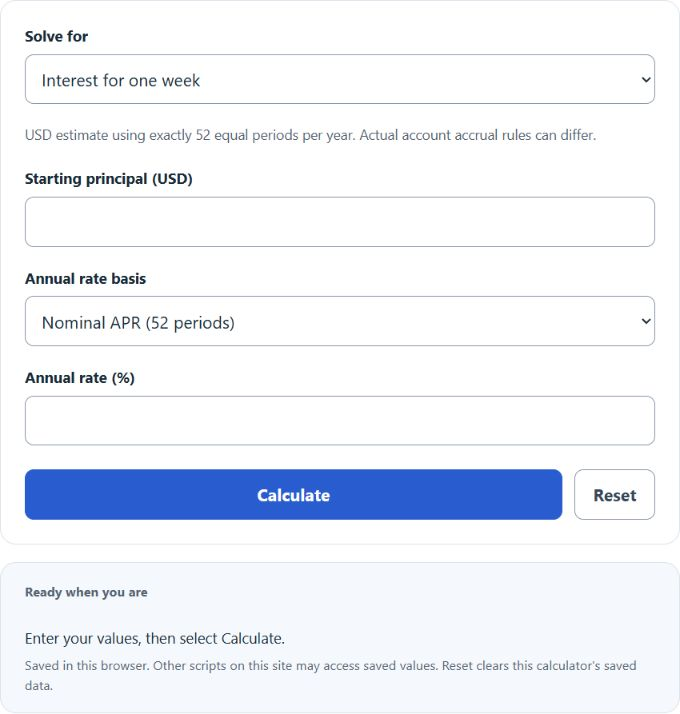
Calculate weekly interest on a balance from its APR or APY, with daily and monthly equivalents, project weekly compounding, or find the APR.
Weekly Interest Formula
- Iweek = interest charged for one week
- B = current loan balance
- APR = annual interest rate as a decimal (6% = 0.06)
For multiple weeks with simple interest, multiply by the number of weeks: I = B * APR * (weeks / 52). For weekly compounding, use End = B * (1 + APR/52)^weeks. To back into the APR from a known weekly charge, use APR = (I_week / B) * 52. These no-contribution formulas use a constant annual rate and 52 modeled periods per year, ignoring fees and tax. With end-of-week contribution C, weekly compounding adds C[(1+r)n − 1]/r to the balance (Cn when r = 0). The simple model adds Cn without interest on contributions. For APY input, r = (1 + APY)(1/52) − 1.
Reference Tables
Weekly interest on a $10,000 balance at common APRs:
| APR | Weekly rate | Weekly interest | Annual interest |
|---|---|---|---|
| 3% | 0.0577% | $5.77 | $300 |
| 6% | 0.1154% | $11.54 | $600 |
| 10% | 0.1923% | $19.23 | $1,000 |
| 18% | 0.3462% | $34.62 | $1,800 |
| 24% | 0.4615% | $46.15 | $2,400 |
| 29.99% | 0.5767% | $57.67 | $2,999 |
Illustrative annual-rate bands, not current market benchmarks or product recommendations. Actual terms, fees, credit profile, and market conditions determine available rates:
| Range | Status | Typical product |
|---|---|---|
| Below 6% | Low | Mortgage, secured loan |
| 6% to 18% | Moderate | Auto, personal loan |
| Above 18% | High | Credit card, short-term loan |
Worked Example and FAQ
Example. You owe $4,500 on a credit card at 22.99% APR. Under the 52-period model, one-week interest is $4,500 × (0.2299 / 52) ≈ $19.90. Eight weeks accrue $159.16 in simple interest or $161.65 with weekly compounding, with no contributions.
Why divide APR by 52? This tool assumes 52 equal compounding periods per modeled year. A calendar year has more than 364 days. Daily accrual can use a 360- or 365-day basis depending on the account, so seven days at APR/365 is a different calculation.
Does this match what my lender charges? This model does not reproduce an account statement. Many credit cards accrue daily based on account balances; payments, transactions, fees, grace periods, and day-count rules change the charge. The reverse result is an interest-only nominal annualization, not a fee-inclusive APR disclosure.
When should I use compounding? Choose weekly compounding only for a model in which interest is credited each week and then earns interest. Choose simple interest for a model that applies interest only to the starting principal. Use the account agreement for actual accrual and rounding rules.