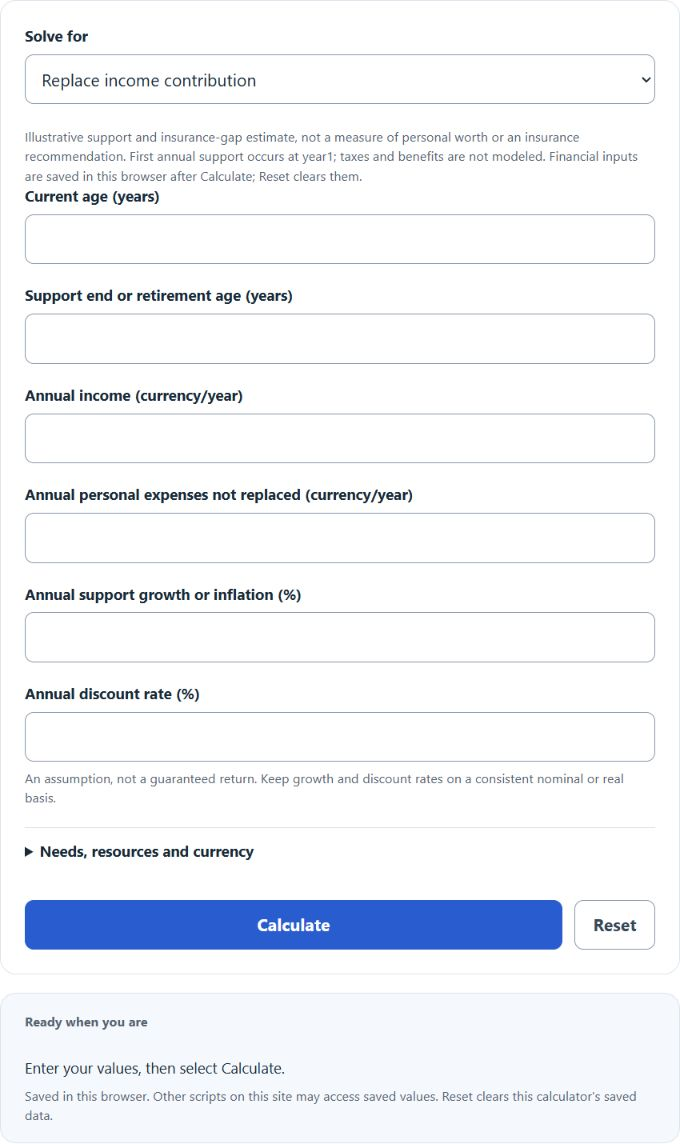
Calculate human life value and estimate additional life insurance need from income, expenses, retirement age, savings, liabilities, and cover.
Human Life Value Formula
The no-growth formula below illustrates support present value plus today’s lump-sum needs. The calculator additionally supports growth: PV = C × [1 − ((1+g)/(1+r))^n] / (r−g), with the equal-rate limit PV = C × n/(1+r). C is the first annual income contribution or annualized household expense, paid at the end of year1; later payments grow at g. Fractional horizons use a smooth formula extension rather than an explicit partial-year payment schedule. Additional coverage = max(0, PV + liabilities + goals − savings − existing cover). Use one currency consistently; the currency control changes display only.
Variables:
- HLV is the Human Life Value (an estimate of the present value of income to be replaced, plus lump-sum needs)
- I is the annual net income to replace (often estimated as annual income minus personal living expenses and other non-replaceable amounts)
- n is the number of years until retirement (the number of annual payments to replace)
- r is the annual discount rate (as a decimal; if the input is a percent, use r = rate/100)
- D is additional debts or other lump-sum financial needs (in today’s dollars)
To estimate the Human Life Value using this model, first estimate the annual net income you want to replace (for example, income minus personal expenses). Then calculate the present value of receiving that amount each year for n years discounted at rate r using the annuity present value factor. Finally, add any additional lump-sum needs such as debts. (If r = 0, the annuity present value simplifies to PV = I · n.)
What is a Human Life Value?
Human Life Value (HLV) is a concept in insurance and financial planning that estimates the economic value of a person’s future earning capacity to their dependents. It is often used to help estimate how much life insurance coverage may be needed so beneficiaries can remain financially secure in the event of the insured person’s death. Depending on the method used, an HLV estimate can consider income, personal and household expenses, debts, time to retirement, inflation, and an expected rate of return (discount rate). HLV is not a measure of a person’s worth in emotional, social, or non-economic terms; it is a tool for financial risk planning.
How to Calculate Human Life Value?
The following steps outline one common way to estimate the Human Life Value:
- Determine the individual’s annual income ($).
- Estimate the annual net income that would need to be replaced (often annual income minus the insured person’s personal living expenses and other non-replaceable costs).
- Determine the number of years until retirement (remaining working years).
- Choose an annual discount-rate assumption, expressed as a percent, and use a consistent nominal or real basis for both growth and discount. The rate is not a guaranteed return.
- Calculate the present value (PV) of the net income stream using: PV = I · (1 − (1+r)−n) / r (or PV = I · n if r = 0).
- Add any additional debts or lump-sum obligations (in today’s dollars) to the PV.
- The support PV plus lump-sum needs is a gross economic estimate. Subtract available savings and existing cover to estimate the additional gap, floored at zero. This is not a complete insurance recommendation or a measure of personal worth; taxes, benefits, survivor income and policy terms may change the need. See NAIC life-insurance guidance.
Example Problem:
Use the following variables as an example problem to test your knowledge.
Annual income ($) = 50,000
Years until retirement (n) = 40
Expenses ($) = 30,000 (so annual net income to replace, I = 50,000 − 30,000 = 20,000)
Discount rate (%) = 5
Additional financial obligations or debts ($) = 20,000; Estimated HLV ≈ 20,000 + 20,000 × (1 − 1.05−40) / 0.05 ≈ $363,182