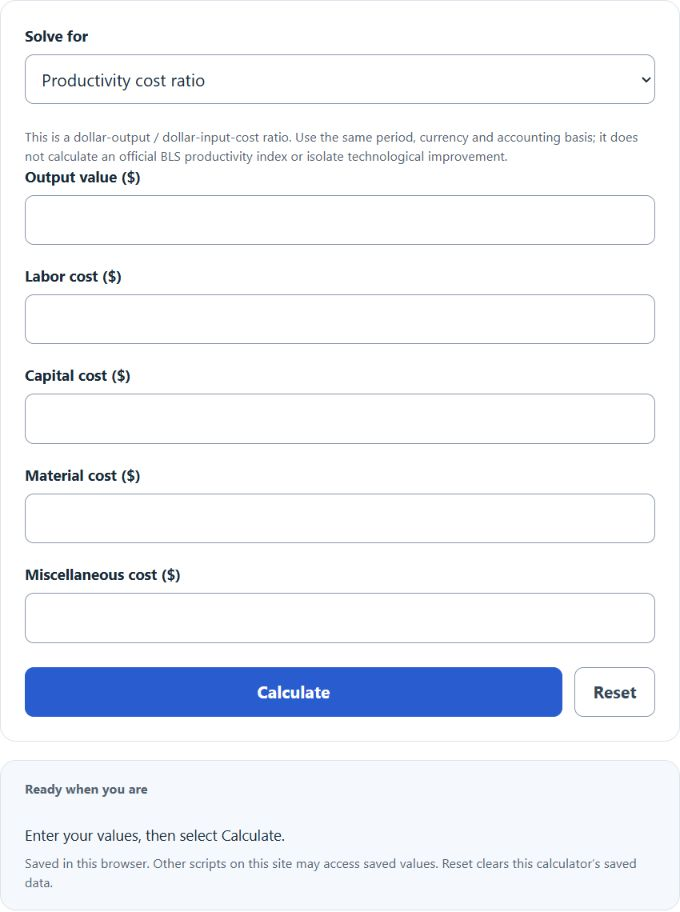
Calculate multifactor productivity from output and labor, capital, material, and miscellaneous costs, or solve any missing value as needed.
- Labor Productivity Calculator
- All Business Calculators
- Labor Efficiency Variance Calculator
- Productivity Index Calculator
Multifactor Productivity Formula
This calculator uses a simple dollar-output to combined dollar-input-cost ratio. Official multifactor or total factor productivity indexes use real output and weighted input quantities instead:
- MP = multifactor productivity (dollars of output per dollar of combined input)
- O = total output value ($) for the period
- L = labor costs (wages, benefits, hours worked x rate)
- C = capital costs (equipment depreciation, lease costs, capital allocation)
- M = material costs (raw materials, components, energy, purchased services)
- X = miscellaneous / overhead costs
An MFP result greater than 1.0 means the operation generates more output value than the total cost of all inputs. An MFP of 1.5, for example, means each dollar of combined input produces $1.50 of output.
What is Multifactor Productivity?
Multifactor productivity measures how efficiently a business or economy converts all inputs simultaneously into output. Unlike single-factor metrics (such as output per labor hour), MFP accounts for the joint contribution of labor, capital, materials, and energy. The residual gap between output growth and the weighted growth of all inputs is what economists attribute to technological progress, process innovation, and efficiency gains. The U.S. Bureau of Labor Statistics (BLS) publishes official MFP data for the private business sector and uses a Tornqvist chain index to aggregate inputs, weighting each by its share of total compensation in adjacent years.
MFP vs. Labor Productivity
Labor productivity (output per hour worked) is the most widely reported productivity metric, but it conflates two separate effects: genuine efficiency gains and capital deepening (workers becoming more productive because they have more or better equipment). MFP strips out capital deepening and isolates the "pure" efficiency improvement. A business can show rising labor productivity while MFP is flat or declining if it is simply substituting capital for labor without improving overall efficiency. BLS data illustrate this clearly: from 2004 to 2016 US manufacturing labor productivity grew modestly, but MFP declined an average of 0.3% per year, revealing that output gains came largely from capital investment rather than efficiency.
U.S. MFP Benchmarks (BLS Data)
BLS publishes productivity indexes and growth rates. The dated observations below describe official real productivity measures and are not benchmarks for this calculator’s nominal dollar-cost ratio.
| Period / Sector | Avg. Annual MFP Growth |
|---|---|
| Private business sector, 1987-2024 (March 2025 release) | +0.9% |
| Private business sector, 2007-2019 (March 2025 release) | +0.6% |
| Private business sector, 2019-2024 (March 2025 release) | +1.0% |
| Private business sector, 2024 (December 2025 revision) | +1.5% |
| Manufacturing sector, 1992-2004 | +2.0% |
| Manufacturing sector, 2004-2016 | -0.3% |
| Management of companies, 2019-2024 | +3.0% |
| Mining / Professional & Technical services, 2019-2024 | +2.5% |
If this dollar-cost ratio rises from 1.50 to 1.53, the ratio increases by 2.0%. That nominal change does not by itself establish real productivity growth and should not be compared directly with BLS growth rates.
Example Calculation
A small electronics assembly operation wants to assess its monthly MFP. Output for the month was $80,000. Inputs: labor $12,000, capital (equipment depreciation + lease) $18,000, materials $30,000, overhead $5,000.
MP = $80,000 / ($12,000 + $18,000 + $30,000 + $5,000) = $80,000 / $65,000 = 1.23
A cost ratio of 1.23 means the operation generates about $1.23 of output per $1.00 of entered input costs. A rise from 1.23 to 1.27 is approximately 3.3% using those rounded ratios. A monthly nominal ratio change cannot be compared directly with an annual BLS real productivity growth rate or used alone to infer efficiency improvement.