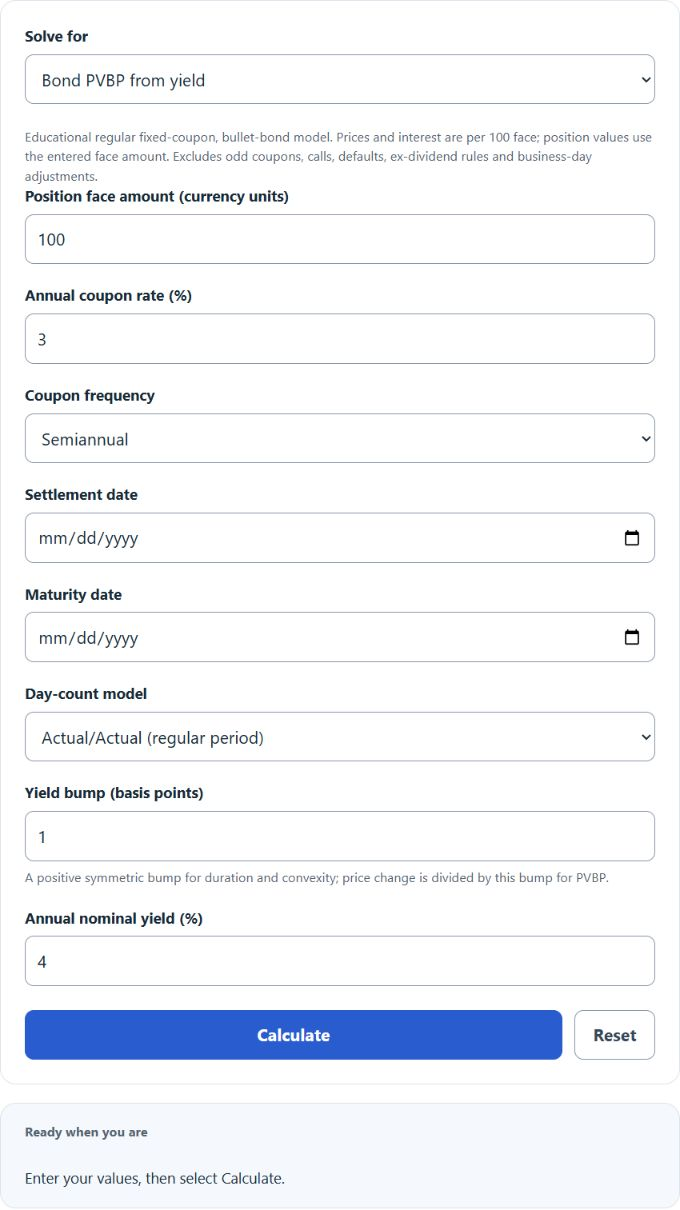
Calculate bond PVBP/DV01 from notional, coupon, settlement, maturity, yield or clean price, with duration, convexity and basis point conversions.
PVBP Formula
The following first-order approximation estimates PVBP magnitude from modified duration and dirty price. Use a consistent per-100 or total-position price basis; the result has the same currency and position basis as the entered price. A +1 bp yield change gives an approximately negative price change for a conventional positive-duration bond.
- Where PVBP is the price value basis point
- MD is the modified duration
- DP is the dirty price
To calculate the PVBP multiply the modified duration by the dirty price, then divide by 10,000.
What is PVBP?
Definition:
PVBP, short for price value basis point, measures bond price sensitivity to a one-basis-point yield change. It depends on modified duration and dirty price. The bond mode instead reprices regular fixed-coupon cash flows after a positive yield bump and divides the price decrease by the bump in basis points; it also reports central duration and effective convexity. Large bumps give a finite-difference average rather than an exact local derivative.
Dirty price equals clean price plus accrued interest at settlement. Bond inputs and reported prices are per 100 face; position PVBP scales by face amount/100. Coupon dates are anchored to maturity with end-of-month preserved. Actual/Actual and 30/360 use the remaining coupon-period fraction for discounting; Actual/365 Fixed uses actual dated cash-flow exponents and annual coupon × actual elapsed days/365 for accrued interest. These are explicit educational conventions; odd coupons, ex-dividend rules, business-day adjustments, calls and defaults are excluded.
How to Calculate PVBP?
Example Problem:
The following example outlines the steps and information needed to calculate PVBP.
First, determine the modified duration. With the help of the calculator linked above, the modified duration is found to be 12.
Next, determine the dirty price of the bond. This is found to be $20,000.00 for this example.
Finally, calculate the PVBP using the formula above:
PVBP = MD * DP * .0001
PVBP = 12* 20,000 * .0001
PVBP =$24.00