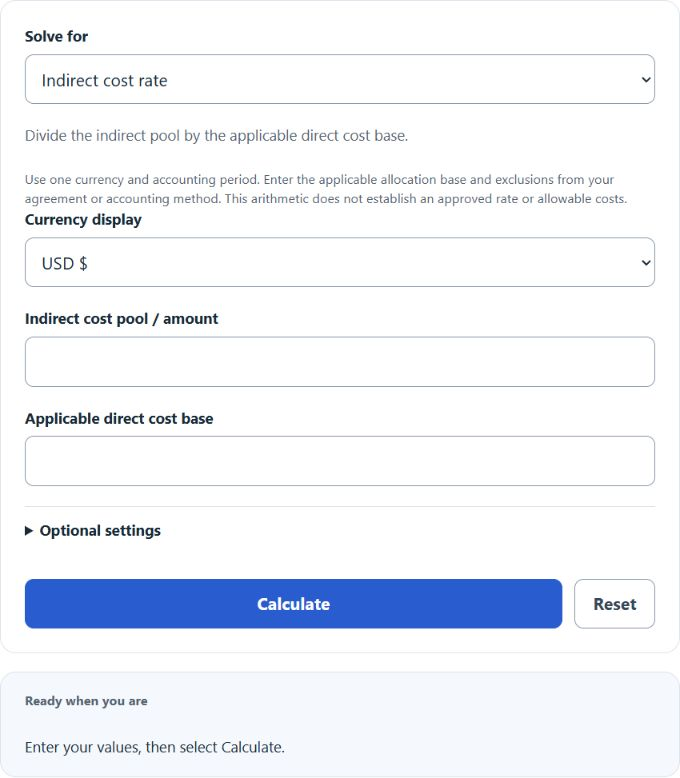
Calculate an indirect cost rate or amount, reverse-solve the applicable base, and plan total budgets with exclusions and comparison-rate recovery.
- All Business Calculators
- Indirect Costs Calculator
- Direct Labor Costs Calculator
- Manufacturing Overhead Calculator
- Predetermined Overhead Rate Calculator
- Unit Product Cost Calculator
- Total Cost Calculator
Indirect Cost Rate Formula
The indirect cost rate expresses an indirect cost pool as a percentage of its applicable allocation base. Use the same period and base definition throughout. For a grant or contract, use the rate, cost classification and exclusions required by the applicable agreement; this calculator does not establish an approved rate.
- ICR = indirect cost rate, as a percentage
- TIE = total indirect expenses, in dollars
- DCB = direct cost base, in dollars
To calculate total indirect expenses, the formula is rearranged:
To calculate the direct cost base, the formula is rearranged again:
- Calculate indirect cost rate: enter total indirect expenses and direct cost base.
- Calculate total indirect expenses: enter indirect cost rate and direct cost base.
- Calculate direct cost base: enter total indirect expenses and indirect cost rate.
Common Direct and Indirect Cost Categories
Use a consistent allocation base when applying an indirect cost rate. The examples below are illustrative; treatment depends on the circumstances and applicable accounting or award requirements. Avoid counting the same cost as both direct and indirect.
| Cost category | Usually treated as | Example |
|---|---|---|
| Direct labor | Direct cost base | Wages for employees working on a specific project |
| Direct materials | Direct cost base | Materials used for one contract or job |
| Rent | Indirect expense | Office or facility rent shared across projects |
| Utilities | Indirect expense | Electricity, water, and internet used by the business |
| Administrative salaries | Indirect expense | Accounting, HR, or management support |
Indirect Cost Rate Interpretation
| Indirect cost rate | What it means |
|---|---|
| 25% | Indirect expenses equal $0.25 for every $1.00 of direct cost base. |
| 50% | Indirect expenses equal $0.50 for every $1.00 of direct cost base. |
| 100% | Indirect expenses equal the full amount of the direct cost base. |
| 150% | Indirect expenses are 1.5 times the direct cost base. |
Example Section
Example 1: Calculate the indirect cost rate
You have $40,000 in total indirect expenses and a $100,000 direct cost base.
The indirect cost rate is 40%.
Example 2: Calculate total indirect expenses
You have a direct cost base of $250,000 and an indirect cost rate of 32%.
The total indirect expenses are $80,000.
FAQ Section
What is an indirect cost rate?
An indirect cost rate is the percentage used to allocate shared costs to a direct cost base. Shared costs can include rent, utilities, administrative salaries, insurance, and other overhead costs that support more than one project or activity.
What should be included in the direct cost base?
The direct cost base depends on your accounting method. It may include direct labor, direct materials, or total direct costs. The important point is consistency. If you calculate a rate using one type of base, apply that rate to the same type of base.
Why can the indirect cost rate be over 100%?
An indirect cost rate can be over 100% when total indirect expenses are greater than the direct cost base. For example, if indirect expenses are $120,000 and the direct cost base is $100,000, the rate is 120%.