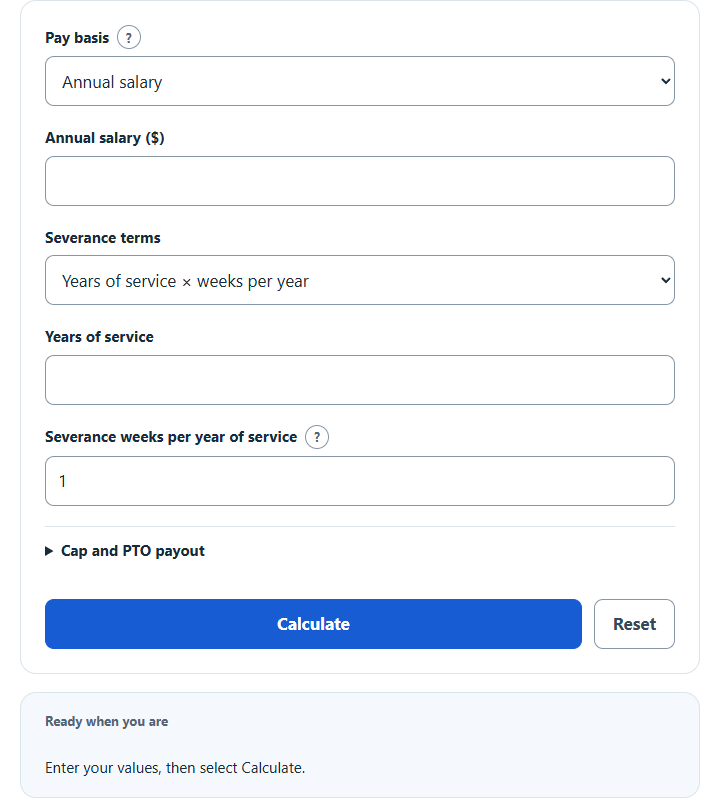
Estimate severance pay from your salary, weekly pay or hourly wage and years of service, at 1 week per year or your offer’s rate, plus unused PTO payout.
Severance Pay Formula
This calculator estimates a gross package from the terms you enter. Under a service-based offer, severance pay is weekly pay multiplied by years of service and the offered weeks per year. Alternatively, enter known total severance weeks. A stated cap can reduce the applied weeks.
SP = W * (Y * WY)
If PTO is payable under the applicable terms and law, this estimate values each day as weekly pay divided by the entered paid workdays per week. Blank workdays assumes five; verify the actual valuation method in your policy. The payout is added to severance:
PTO = (W / N) * D
 Total = SP + PTO
Variables:
- SP is the gross severance pay, in dollars, before taxes and deductions
- W is your weekly pay. From an annual salary, W = salary / 52; from an hourly wage, W = hourly rate * hours per week
- Y is your years of service with the employer (decimals allowed, e.g. 6.5 years)
- WY is the weeks of severance offered per year of service; the calculator starts at a common 1 week per year; enter your applicable rate
- D is the number of eligible unused PTO days paid out. N is the paid workdays per week used for the estimate, five when blank; the assumed daily rate is W / N
Choose annual salary, weekly pay, or an hourly wage with hours per week. Annual pay uses 52 weeks; hourly pay multiplies the stated wage by hours without adding overtime premiums. Enter years and an offered weeks-per-year rate, or select known total weeks. Optional settings apply a cap and eligible PTO days with an explicit workday assumption. Blank cap means no cap; a zero cap means no severance weeks. Blank PTO means zero. Severance and PTO each round half up to cents using unrounded weekly pay, then add. Actual payroll or plan rounding can differ.
Use the rate, cap, eligibility rules and payout terms stated in your applicable plan or offer. Comparison rates and caps are illustrative scenarios, not universal entitlements or industry standards. A package may involve a release of claims or other conditions; review its actual terms before deciding whether to accept it.
The monthly equivalent is the gross package averaged over the severance-week period using 52 weeks per year and 12 months per year. It includes any PTO payout, does not describe the payment schedule, and is undefined when severance weeks are zero. Taxes, deductions, benefit continuation and unemployment eligibility are not calculated.
US federal severance after a reduction in force
Select US federal severance (RIF) for a conditional gross estimate. Supply agency-confirmed basic pay, creditable service and age at separation. Annual pay assumes a fixed 40-hour schedule; for another schedule, use a payroll-verified weekly rate. Eligibility, including appointment, service and retirement conditions, must be checked with agency HR.
Following the OPM estimation worksheet, the annual-pay option divides annual basic pay by 2,087, rounds the hourly rate to cents, then multiplies by 40. This differs from the general offer mode's annual salary divided by 52.
Basic allowance weeks are one per service year through ten and two thereafter. Incomplete service years count only full three-month blocks. The age multiplier adds 2.5% per full quarter-year over age 40. Payable weeks = max(0, min(age-adjusted allowance weeks, 52) − federal severance weeks previously received). Fund = weekly basic pay × payable weeks. See 5 CFR 550.707 and 550.712.
For example, verified weekly basic pay of $1,500, service of 20 years 4 months, and age 45 years 8 months gives 30.5 basic weeks and a 1.55 age multiplier. With no previous severance, the fund is $70,912.50 over 47.275 weeks. The ordinary full biweekly payment is $3,000; the last may be smaller. Taxes, PTO and benefits are excluded, and reemployment may stop or suspend payments. Review the OPM eligibility and payment guidance.
India: lay-off and retrenchment are different
The India modes estimate individual compensation components in rupees after you confirm coverage and eligibility. The Industrial Relations Code, 2020 distinguishes temporary lay-off from retrenchment. These estimates are not gratuity calculations or a total settlement.
Retrenchment component: daily average pay × applicable days per year × credited service years. The general rate is 15 days; a remaining period exceeding six months adds one credited year. Enter payroll-confirmed daily average pay, not automatically last-drawn monthly salary divided by 26. At INR 1,000 per day, five years plus more than six months gives INR 90,000 at the 15-day rate.
Temporary lay-off component: 50% × daily basic wages plus dearness allowance × eligible payable days. At INR 1,000 per day for 20 eligible days, this is INR 10,000. Exclude weekly holidays; agreements and rules after 45 days can affect payable days. Confirm the correct pay basis and days with payroll. Notice pay, gratuity, re-skilling contributions and possible set-offs are not included.
Severance Weeks and Pay by Years of Service
This illustrative table compares offers of 1 and 2 weeks per service year, with no cap or PTO payout, for 1 to 20 years and $1,500 weekly pay (a $78,000 annual salary under the 52-week assumption). These rates are examples, not a statement of what an employer must or typically will offer.
| Years of service | Weeks at 1 wk/yr | Weeks at 2 wk/yr | Pay at 1 wk/yr | Pay at 2 wk/yr |
|---|---|---|---|---|
| 1 | 1 | 2 | $1,500 | $3,000 |
| 2 | 2 | 4 | $3,000 | $6,000 |
| 3 | 3 | 6 | $4,500 | $9,000 |
| 4 | 4 | 8 | $6,000 | $12,000 |
| 5 | 5 | 10 | $7,500 | $15,000 |
| 6 | 6 | 12 | $9,000 | $18,000 |
| 7 | 7 | 14 | $10,500 | $21,000 |
| 8 | 8 | 16 | $12,000 | $24,000 |
| 9 | 9 | 18 | $13,500 | $27,000 |
| 10 | 10 | 20 | $15,000 | $30,000 |
| 11 | 11 | 22 | $16,500 | $33,000 |
| 12 | 12 | 24 | $18,000 | $36,000 |
| 13 | 13 | 26 | $19,500 | $39,000 |
| 14 | 14 | 28 | $21,000 | $42,000 |
| 15 | 15 | 30 | $22,500 | $45,000 |
| 16 | 16 | 32 | $24,000 | $48,000 |
| 17 | 17 | 34 | $25,500 | $51,000 |
| 18 | 18 | 36 | $27,000 | $54,000 |
| 19 | 19 | 38 | $28,500 | $57,000 |
| 20 | 20 | 40 | $30,000 | $60,000 |
Example Problems
Example 1: Salaried employee.
You earn a $78,000 annual salary and are laid off after 6 years. Your employer offers 2 weeks of severance per year of service. First find weekly pay: W = 78,000 / 52 = $1,500. Severance weeks = 6 * 2 = 12 weeks.
SP = 1,500 * 12 = $18,000 gross severance. Spread over the 12 weeks it replaces, that works out to a monthly equivalent of $6,500 while it lasts.
Example 2: Hourly employee with PTO payout.
You earn $25 per hour and work 40 hours per week, so W = 25 * 40 = $1,000. You have 3.5 years of service and are offered 1 week per year, so severance weeks = 3.5 * 1 = 3.5, and SP = 1,000 * 3.5 = $3,500.
Assume your terms pay out 4 unused PTO days and use five equal paid workdays per week. The estimated daily rate is 1,000 / 5 = $200, so PTO = 200 × 4 = $800 and the total package is 3,500 + 800 = $4,300 gross. A different applicable valuation method can change the PTO payout.
Frequently Asked Questions
Is severance pay required by law?
The Fair Labor Standards Act does not require severance pay. Whether severance is owed depends on applicable law and the terms and eligibility rules of an employment agreement, collective agreement or benefit plan. A written promise is not an unconditional entitlement in every case.
Federal WARN is distinct from ordinary severance. It generally requires covered employers to provide 60 calendar days’ advance written notice of qualifying plant closings or mass layoffs, subject to exceptions. Inadequate notice can create back-pay and benefit liability for the violation period, up to 60 days. Certain voluntary payments may offset liability; pay instead of notice is not a universal statutory alternative. See the Department of Labor WARN FAQs.
How is severance pay taxed?
Severance generally constitutes taxable supplemental wages. Under IRS Publication 15 (2026), section 7, an employer may use 22% federal income-tax withholding for separately identified supplemental wages totaling no more than $1 million in the calendar year if income tax was withheld from regular wages in the current or preceding calendar year; the aggregate method is another option. Without that prior regular-wage withholding, the aggregate method applies. The portion of cumulative supplemental wages above $1 million is withheld at 37%; payments from businesses under common control count together. Applicable payroll and state taxes may also apply. Withholding is not final tax liability. This calculator estimates gross amounts only.
Does severance affect unemployment benefits?
It varies by state. Some states pay unemployment benefits alongside severance, while others delay or reduce benefits until the severance period ends, especially when severance is paid as salary continuation rather than a lump sum. Report any severance when you file your claim, and check your state unemployment office's rules so you know when benefits will start.