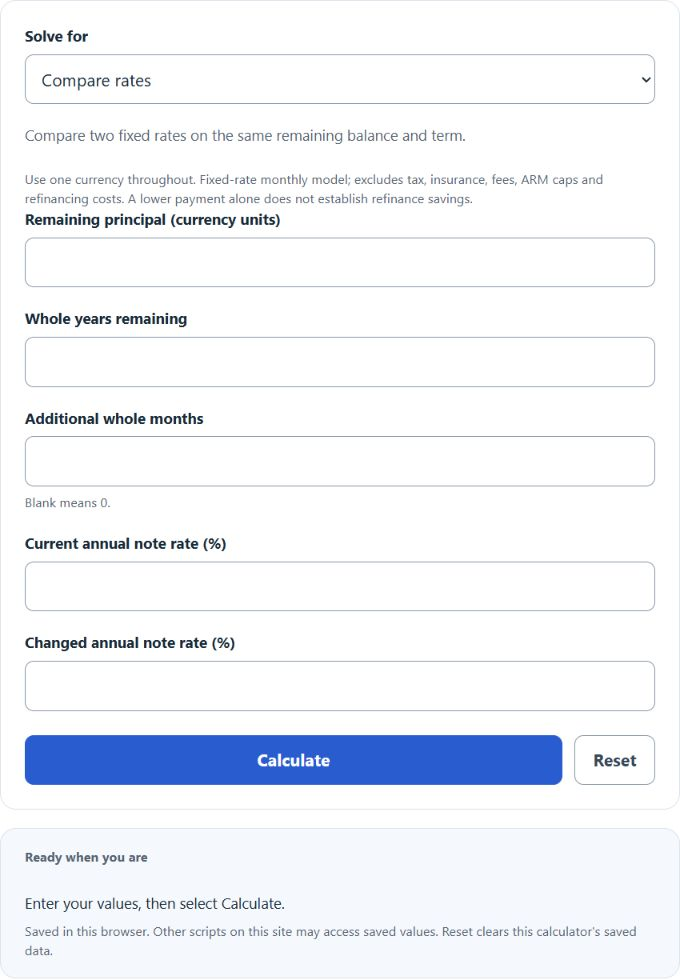
Compare mortgage payments and remaining interest after a rate change, or reverse-solve the rate for a target payment, with stress cases and worked formulas.
Mortgage Rate Change Formula
The following equation is used to calculate the monthly mortgage payment, which can then be compared between two different interest rates to assess the impact of a rate change.
- Where M is the monthly mortgage payment ($/month)
- P is the loan principal ($)
- r is the monthly decimal interest rate (annual percent / 1200)
- n is the number of monthly payments (12 × whole years + additional whole months), from 1 to 1,200
To evaluate the impact of a mortgage rate change, calculate the payment (M) at both the current interest rate and the proposed new rate, then compare the difference in monthly payments and remaining interest over the same entered remaining term. Fees, tax, insurance, rate caps and refinancing costs are excluded.
What is a Mortgage Rate Change?
Definition:
A mortgage rate change refers to an increase or decrease in the interest rate applied to a home loan. This change can significantly affect your monthly mortgage payments and the total amount of interest paid over the course of the loan.
How to Calculate Mortgage Rate Change?
Example Problem:
The following example outlines the steps and information needed to calculate the impact of a mortgage rate change.
First, determine the principal and the current loan details. Suppose you have a loan balance of $300,000 with 20 years (240 months) remaining and a current annual interest rate of 4%. The current monthly interest rate is 4% / 12 = 0.333% (0.00333 in decimal form).
Next, determine the proposed new interest rate. Assume you’re considering refinancing to a new annual interest rate of 3.5%, making the new monthly interest rate 3.5% / 12 = approximately 0.2917% (0.002917 in decimal form), still over 20 years.
Using the unrounded monthly rates, the current payment is $1,817.94 and the changed payment is $1,739.88, a monthly decrease of $78.06. Remaining interest decreases from $136,305.84 to $117,571.00, a difference of $18,734.84 over the same 240 months. These figures exclude refinancing costs.
FAQ
Why do mortgage rates change?
Mortgage rates change due to various economic factors such as inflation, Federal Reserve policies, and overall demand in the lending market. Lenders adjust rates to manage risk and respond to market conditions.
How much can a small change in interest rate save me?
For the same principal and remaining term, a lower fixed rate reduces principal-and-interest payments and remaining interest. The amount depends on the inputs. Refinancing fees, a changed term and how long you keep the loan can offset savings.
When should I consider refinancing my mortgage?
Refinancing may be beneficial when interest rates are lower than your current rate. However, you should also consider closing costs, the remaining loan term, and how long you plan to stay in your home before deciding if refinancing is worthwhile.